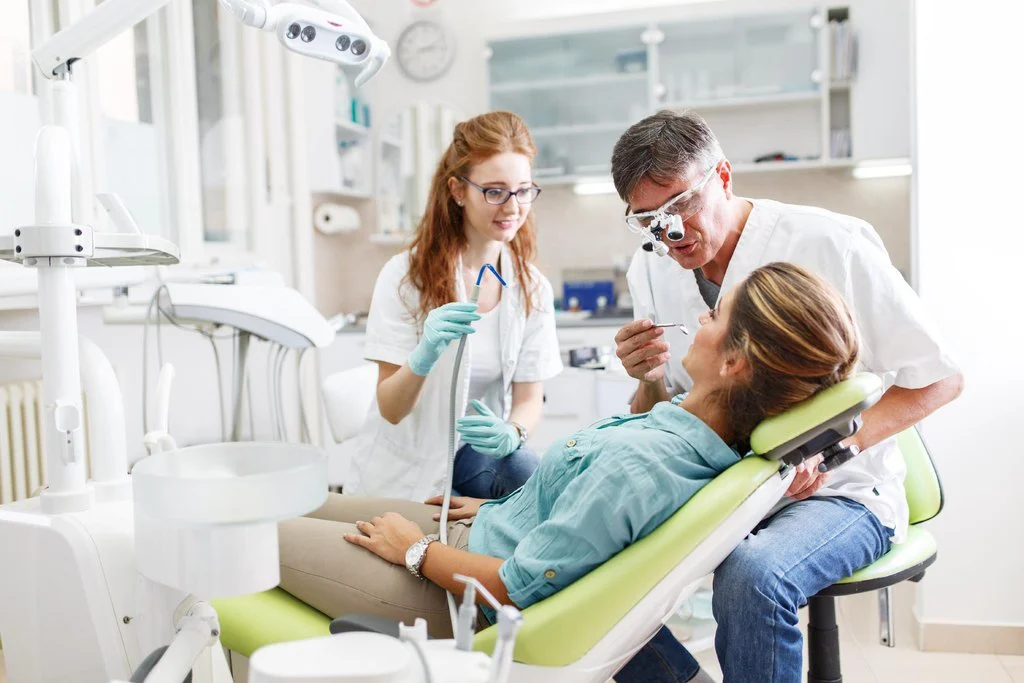
Existing dental practices generally have an advantage when looking for money to purchase equipment, diagnostic machines, treatment devices, sterilization machinery, or other significant purchases. As opposed to new practices, they are able to prove their operating history, demand for services, recurring revenues, and financial statements that reveal the way their business operates. All of this will be helpful to the bank in evaluating their risk as well as the ability of the business to handle one more payment obligation. A good dental equipment loan application for a dental practice will need to include more information than just the equipment that will be purchased.
Qualification Requirements for Dental Equipment Loan
Let’s look into some of the qualification requirements to get the loan:
Business History and Revenue
It is ideal if there are several years of experience for the business practice. A consistent track record of revenues enables lenders to better gauge the cash flow of the business practice and its capability to repay its debts. Lenders may analyze the practice’s annual revenues, profitability, cash flow, number of patients, and consistency of the income instead of one very good year of the business practice. It is much easier for a practice with consistent revenues to convince dental equipment loan lenders since they have enough information to determine the capacity to repay their loans.
Credit and Financial Records
Credit history continues to be an integral component in financing decisions despite the fact that a particular practice has been operating successfully for many years. Lenders will examine business and personal credit histories depending on the nature of the practice, guarantee requirements, and the finance provider. Accounting information will be critical since dental equipment loan lenders require proof that the financial information provided is consistent with reality. The tax returns, profit and loss accounts, balance sheets, bank statements, and existing debts may make up part of the underwriting.
Equipment and Loan Details
The actual equipment can affect how the dental equipment loan is assessed by the lending institution as well. The useful life, resale value, and technology life cycle of dental chairs, imaging machines, digital scanning machines, computer-aided design and manufacturing, sterilization equipment, and other specialized assets may vary. The lending institution will then take into consideration the cost of the equipment, its useful life, the company producing it, the condition of the equipment, and the reason why it needs to be purchased in order to determine the most suitable dental equipment financing option.
Factors Influencing Approval and Pricing
Many factors might impact both the approval process as well as the terms that will accompany the financing. Creditworthiness is a major factor. However, many lenders take into consideration other factors like revenue stability, profit, total current debt, cash balance, and the general capability of the practice to repay another obligation. The total funding requirement itself could be a factor in how the analysis is made, especially in case the total amount is substantial relative to annual revenues or cash flows.
Equipment value and the period of its usefulness could play some role as well in relation to the evaluation of the security and risk of recovery by the lender. Terms of the dental equipment loan itself could have some impact on the entire analysis since longer periods could lower monthly payments but increase the repayment period. Some lenders might focus more on business performance, whereas some might look at security and guarantees or just pure credit considerations.
Comparing Dental Equipment Loan Programs
Let’s look into some of the loan options for dental practices:
Bank Equipment Loans
Financial institutions might serve well for dental offices that already possess a reputable track record in terms of finances and experience dealing with financial institutions. Lenders usually employ a thorough underwriting process that includes business history, credit history, cash flow, liabilities, and the plan of equipment acquisition. A financial institution may offer a way to go about the financing procedure in a systematic manner if the office is purchasing expensive equipment and would like to make repayments systematically. However, the approval process might take more time if the financial institution requests extensive documentation.
Online Equipment Financing
Online financing sources can serve as a good solution for practices that are looking for an easier application procedure. Many online financing sources have online application forms and use electronic documents in order to minimize paperwork and make information processing faster. Such an approach will be convenient for the practice that wants to change its equipment but doesn’t want to go through the whole process of borrowing from banks. However, time cannot be the sole selection criterion for owners. It is important to analyze the term of the dental equipment loan, total cost of the loan, required documentation, collateral, and early repayment terms.
Vendor Financing
The equipment manufacturer or supplier might have financing arrangements available directly or via lending companies. The financing scheme from the vendor may make the procurement process more efficient since the financing application will be tied directly to the equipment procurement itself. This method may come in handy when the dental practice has already decided which piece of equipment or technology to buy. At times, vendor financing might include specific payment schemes built around certain classes of equipment. The owner also needs to evaluate the financing scheme against other available options.
Leasing Programs
Equipment leasing can offer another approach for getting equipment without necessarily having to own the piece of equipment immediately. A dental equipment lease is ideal for a dental practice that updates its technology often and prefers to deal with its equipment through regular payments rather than owning all its assets. The terms under which this happens can vary greatly from one contract to another, especially when it comes to matters such as who is responsible for the maintenance of the equipment, the option to renew, buy out, and what happens at the end of the term.
Final Words
Many established practices have certain strengths that new practices do not necessarily have to offer, such as a longer history, better revenue trend analysis, and detailed accounting of income and expenses. These may provide a basis for obtaining funds by presenting finances in an effective way and purchasing equipment that has practical purposes. It is possible to compare banks, equipment manufacturers’ financing, and leasing to find out how flexible the loan terms are. The optimal dental equipment loan should fit cash flow, commitments, the lifetime of equipment, and the overall business strategy of financing.
Read More: Smart Investing: How to Build a Diversified Portfolio